

First Resources: A Stock Worth Watching After a Sharp 48% Pullback (12 Nov 2026)
First Resources has been one of the more heavily sold-down plantation stocks in recent weeks, declining about 48% from its high of S$5.24 on 18 September to trade at $2.70 on 12 Nov 2026.
Several factors may have contributed to the weakness, including:
- Lower crude palm oil (CPO) price expectations.
- Concerns that earnings may have peaked following an exceptionally strong period.
- Profit-taking after the stock’s strong share price rally earlier this year.
- A broader de-rating of plantation stocks globally.
- ESG and haze-related concerns weighing on sentiment.
While these factors should not be dismissed, the extent and speed of the recent decline suggest that the stock may be approaching levels where investors could begin to re-examine its value proposition.
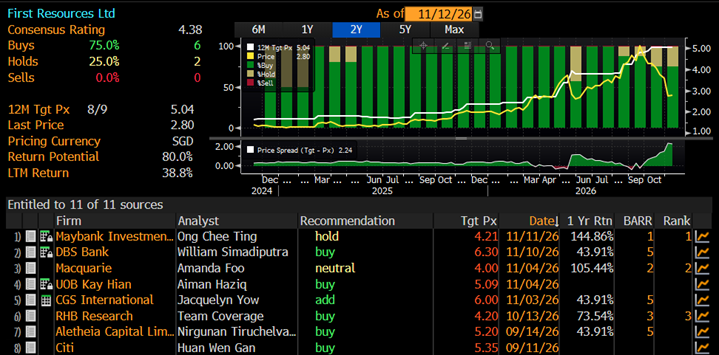
Based on Bloomberg (Figure 1), the average analyst target price stands at S$5.04. First Resources is currently trading at around 7.6x FY27F earnings with an estimated dividend yield of approximately 8.5%.
Figure 1: Consensus target price for First Resources is S$5.04
That said, analyst estimates could change given ongoing volatility in CPO prices and uncertainties surrounding haze-related developments. Nevertheless, the recent correction has been severe from 29 Oct through 10 Nov, with the stock falling S$1.09 or around 30% over just eight consecutive trading sessions. Technical indicators also suggest an oversold condition, with RSI at approximately 17.6 on 10 Nov.
Key Points Worth Monitoring
1) Near-term earnings remain a potential catalyst
Based on some analysts that I speak to, industry read-throughs suggest upcoming 3Q results from First Resources could show improvements both quarter-on-quarter and year-on-year, supported by healthy operating conditions across the plantation sector. First Resources likely reports 3QFY26F results on or around 13 Nov.
2) Long-term palm oil demand remains supportive
Indonesia’s implementation of the B50 biodiesel programme is expected to increase domestic palm oil consumption and could provide structural support for demand over time. Based on DBS Research, this B50 biodiesel programme just started ramping up last month, with optimal level likely to reach in 2027.
3) Valuation has become more compelling after the sharp correction
First Resources has fallen 48% from its recent high and is currently trading at around 7.6x FY27F earnings with an estimated dividend yield of about 8.5%, based on consensus forecasts.
4) The business continues to benefit from production growth and integration
Contributions from the ANJ acquisition, together with its integrated operations across plantations, milling, refining and biodiesel, provide avenues for longer-term earnings growth.
5) A recovery in CPO prices could support sentiment and earnings
While CPO prices have retraced from recent highs, long-term underlying industry fundamentals remain supported by biodiesel demand, edible oil supply dynamics and weather-related supply risks.
(Examples) of Key Risks
1) CPO price volatility
CPO prices have retreated 19% from a high of MYR5,049 on 17 Sep to touch a low of MYR4,088 before bouncing higher. Thus, a significant decline in palm oil prices would directly impact earnings and cash flow.
2) Weather-related risks
Weather anomalies including droughts or adverse climatic conditions that could reduce Fresh Fruit Bunches (FFB) yields and production volumes.
3) Regulatory and policy risks in Indonesia
This may include changes to export levies, biodiesel mandates or repatriation requirements that may affect profitability.
Closing Thoughts
Based on current analyst reports and market expectations, First Resources continues to possess several positive long-term fundamentals, including production growth, exposure to palm oil demand trends and attractive dividend yields.
That said, commodity-related stocks are inherently cyclical, and investors should remain mindful of the risks associated with CPO prices, weather conditions and regulatory developments. Following the recent sharp correction, First Resources may be a counter worth monitoring closely as more information emerges from upcoming earnings releases and developments in the palm oil market.
Disclaimer
Please refer to the disclaimer HERE.
P.S: I have informed my clients on First Resources past few days.